Before the first tap: Why money habits must be taught at home
India has built world-class financial infrastructure faster than it has built the habits to use it well. That lesson begins with parents.
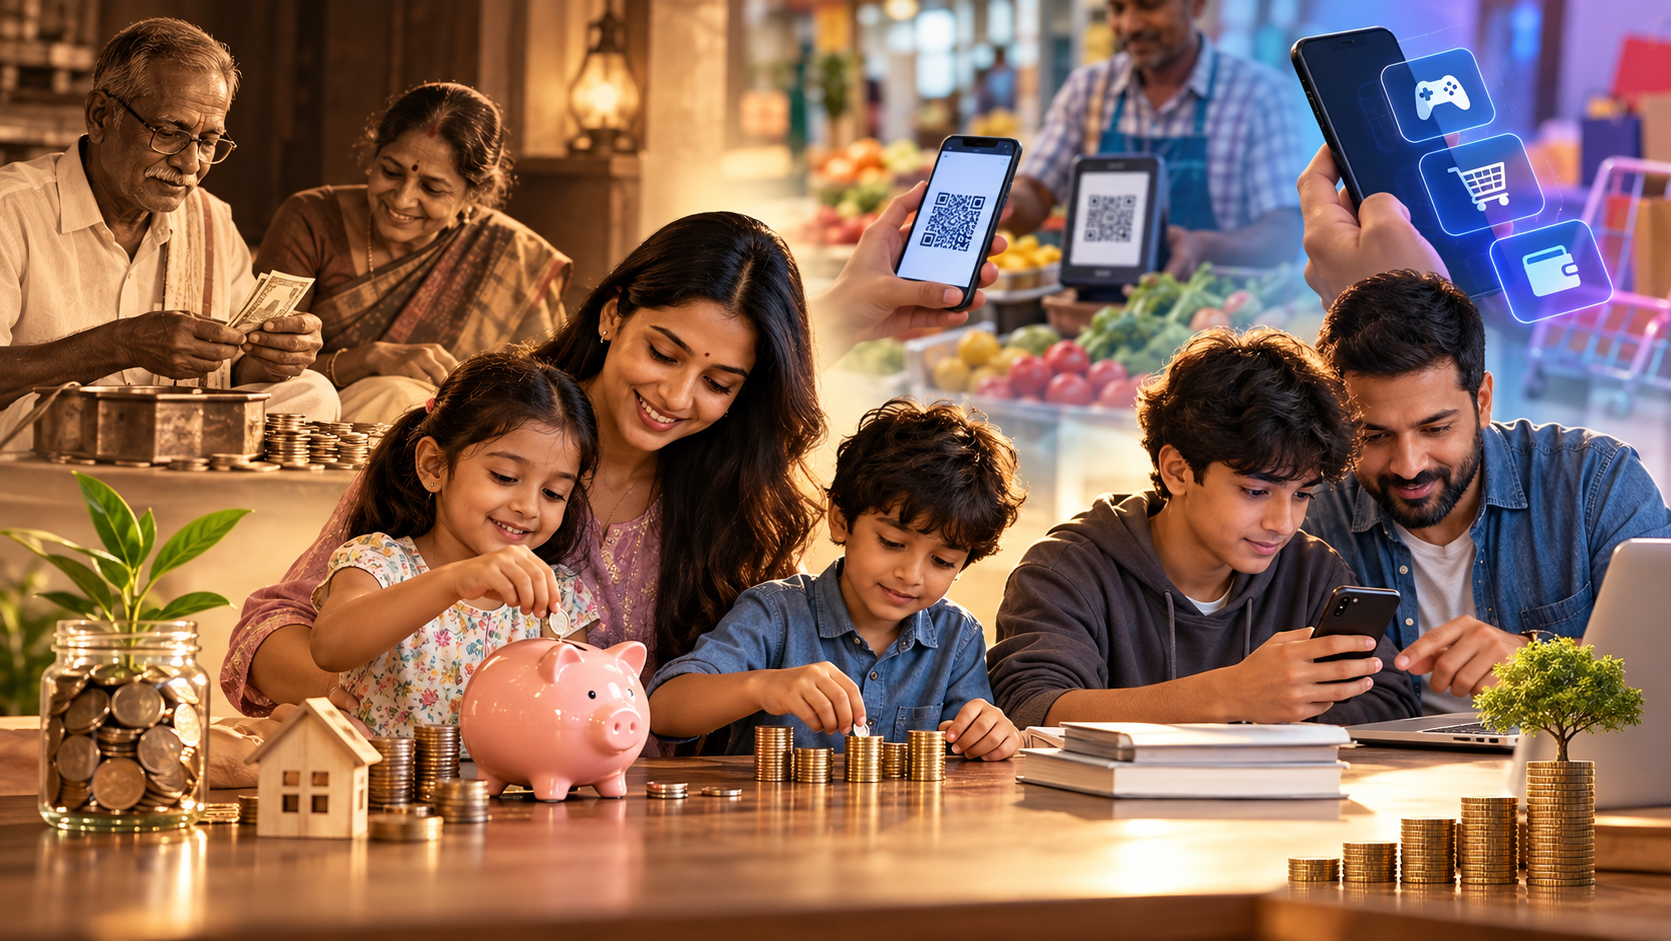
Every generation of Indian parents has taught its children about money in its own way. Mine learnt it by watching elders count coins at the end of the day, weigh each purchase, and put something aside, however small, for a bad season. The lessons were rarely spoken. They were simply visible.
That visibility is disappearing. A child today watches a parent scan a QR code at the vegetable stall, order dinner on an app, and top up a mobile game in seconds. Money no longer changes hands; it vanishes with a tap. At the same time, credit has never been easier to obtain. Instant loans and buy-now-pay-later offers arrive on the same phone that carries a teenager’s homework and games.
India’s financial infrastructure has advanced faster than most of the world’s advance countries. Our financial habits have not kept pace. Past surveys have found that only about one in four adults meets its benchmark for financial literacy. Today, we have given our citizens powerful tools without always teaching them how to handle them.
In my years in the business of lending, I have learned that financial distress does not always begin with a lack of money. More often, it begins with a decision taken without understanding: a loan whose true cost was not read, a scheme that promised too much, a repayment date forgotten. These are not failures of intelligence. They are failures of habit, and habits are formed early.
The evidence supports this. A 2013 University of Cambridge study for the UK’s Money Advice Service found that core money habits, such as planning ahead and delaying gratification, are largely formed by about the age of seven. By the time most of us encounter a formal lesson on interest rates, the foundations have already been laid down.
I must add a note of honesty. Research on formal financial education is mixed, and classroom lessons on their own often fade. What endures is practice: small, regular decisions with real consequences, made while the stakes are low. That is why I believe the most important financial educator in any child’s life is not a teacher or a regulator, but a parent.
What can parents do?
For the youngest children, between three and seven, money must be made real again. Letting a child pay cash for a small purchase and count the change teaches that money is finite. Speaking choices aloud (“we can buy this today, or save for something better next month”) teaches that every rupee spent is a rupee that cannot be spent elsewhere. Between eight and twelve, children are ready for goals and patience. A fixed, regular allowance that the child manages, mistakes included, is a better teacher than any lecture. From the age of ten, RBI rules permit minors to open and operate a savings account independently, within limits set by the bank.
Teenagers need the truth about the system they are entering. They should know how a bank account, a debit card and UPI work, and how credit card interest and late fees accumulate. They should understand compounding, and why starting to save at twenty rather than thirty makes a large difference. They should understand inflation, and why idle cash quietly loses value. They should learn the basics of insurance and of not placing every egg in one basket.
Above all, they must learn caution: never to share an OTP or PIN, never to approve a UPI request that claims to “send” them money, and to treat investment tips from social-media personalities with healthy scepticism. The attraction of in-game purchases deserves an honest conversation too.
Parents can also save for their children in ways that double as lessons: a minor’s savings account or recurring deposit, a Public Provident Fund account opened in the child’s name, or the Sukanya Samriddhi Yojana for a daughter. Reviewing the statements together turns a passbook into a classroom.
None of this guarantees wise choices. No upbringing can. But I am convinced that a child who has handled money early, made small mistakes while little was at stake, and watched the adults around them live within their means will be far better prepared for a world in which borrowing, spending and investing are only a tap away.
Our parents taught us by example, often without a word. Our children will need both the example and the words. The conversation should begin before that first tap.
Pic Courtesy: google/ images are subject to copyright