The 2026 IBC Overhaul: Redefining Corporate Recovery and Liquidation in India
Adv Sherry Samuel Oommen:
Adv Sherry Samuel Oommen:
He specialises in the Constitution, tax and corporate laws and has also cleared the final exams of the Institute of Chartered Accountants of India, the Institute of Cost Accountants of India and the Institute of Company Secretaries of India. He has also completed his Masters’s Degree in Commerce, apart from obtaining a Post Graduate Diploma in Business and Corporate Laws from Symbiosis, Pune. The views expressly are personal and should not be construed as a legal opinion.
sherryoommen@nashcp.com
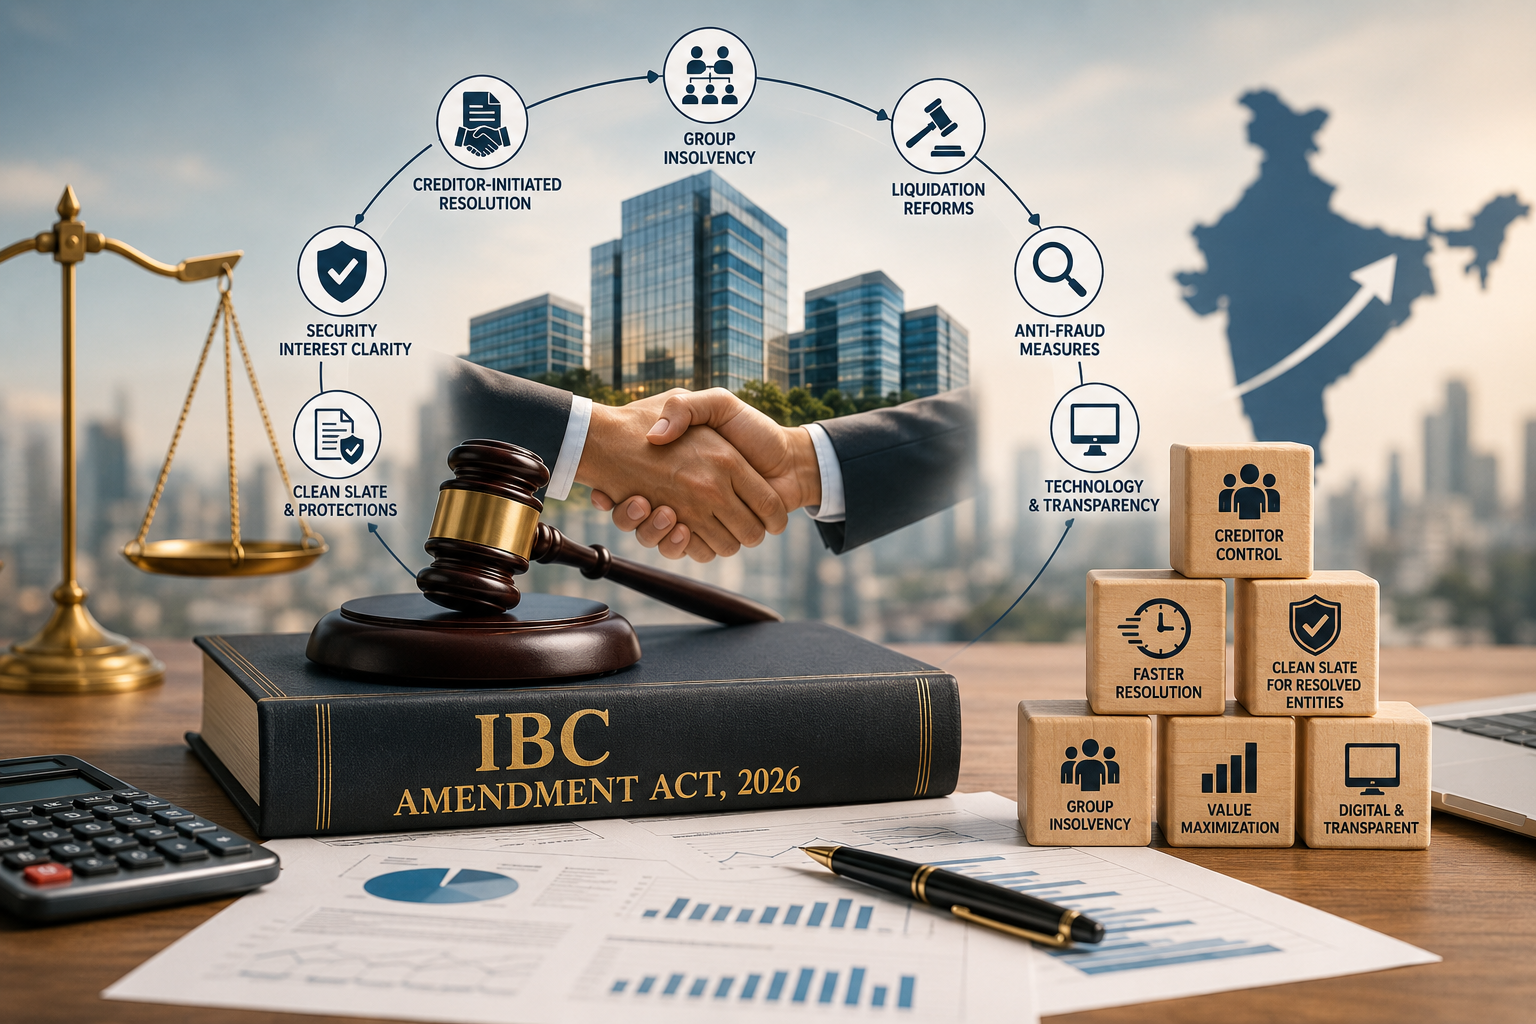
The passing of the Insolvency and Bankruptcy Code (Amendment) Act, 2026 marks a transformative milestone in India’s economic legislation. This is not merely a technical refinement; it is a structural overhaul designed to address the “Three Ds” that have historically plagued the IBC: Delay, Deterioration of asset value, and Disjointed litigation.
By shifting toward a more digital, creditor-supervised, and group-centric model, the 2026 Act aims to restore the IBC’s status as a high-velocity resolution tool. Below is an exhaustive elaboration on the key pillars of the Amendment Act, tailored for both professionals navigating the technicalities and non-professionals seeking to understand the broader impact. This article should not in any manner be construed as a legal opinion in any form or manner whatsoever.
1. The Reconceptualization of Security Interests
One of the most debated aspects of the original 2016 Code was the hierarchy of claims, particularly regarding government dues. The 2026 Act provides a decisive clarification through the amendment of Section 3(31).
Statutory vs. Contractual Charges
Previously, various tax authorities claimed “secured creditor” status based on charges created by tax laws (statutory charges). The Amendment Act now clarifies that a “Security Interest” must be the result of a specific agreement or arrangement between parties—such as a mortgage, hypothecation, or a pledge.
- The Impact: Government dues arising from tax penalties or arrears will no longer bypass the waterfall mechanism by claiming to be secured. This protects the priority of financial institutions and ensures that the “waterfall” under Section 53 remains predictable for investors.
2. The Era of “Group Insolvency” (Chapter VA)
Large corporate failures in India (such as those in the infrastructure and telecom sectors) often involve complex webs of parent companies, subsidiaries, and special purpose vehicles (SPVs). Historically, the IBC treated these as isolated legal entities, leading to fragmented resolutions where the parent was sold to one bidder and the subsidiary to another, destroying synergistic value.
Coordinating Multi-Entity Failures
The introduction of Section 59A allows for the coordination and cooperation of insolvency proceedings across a corporate group.
- Coordination over Consolidation: While it doesn’t necessarily merge the assets of all companies, it allows for a “Group Resolution Professional” and synchronized timelines. This ensures that a bidder can propose a plan for the entire group, maximizing the enterprise value rather than selling it off piece-by-piece.
3. Creditor-Initiated Resolution: The Out-of-Court “Hybrid”
The NCLT has long been the bottleneck of the IBC process. To alleviate this, the 2026 Act introduces the Creditor-Initiated Insolvency Resolution Process (Sections 58A to 58K).
How the New Mechanism Works:
- Notice and Initiation: Financial creditors can issue a notice to a corporate debtor. If the debt is undisputed and meets prescribed conditions, the creditor can initiate resolution without waiting for an upfront NCLT admission order.
- Professional Appointment: The creditor directly appoints the Resolution Professional (RP).
- Minimal Disruption: The management often stays with the Board of Directors, but under the strict oversight of the RP, who has the power to veto resolutions that might harm creditors.
- Strategic Goal: This mimics “Pre-packaged” insolvency but is driven by creditors. It aims to resolve genuine business failures quickly and with minimal judicial friction, leaving the NCLT to handle only the most contentious cases.
4. Reinventing the Liquidation Framework
The 2026 Act acknowledges that once a company moves into liquidation, the goal must be rapid asset monetization to prevent “value leakage.”
Shift to CoC Supervision (Section 35)
In the previous regime, the Committee of Creditors (CoC) largely became defunct once liquidation was ordered, leaving the Liquidator to operate with high autonomy. The Amendment Act changes this:
- Ongoing Oversight: The CoC now supervises the conduct of the liquidation process. This ensures that the commercial wisdom of the lenders continues to guide the sale of assets.
- Claims Continuity: A major cause of delay was the Liquidator re-verifying claims that had already been verified during the resolution (CIRP) stage. Sections 38–42 have been omitted. The Liquidator will now simply maintain and update the claims list from the CIRP stage, significantly accelerating the distribution of proceeds.
The “Dissolution without Liquidation” Option
Under Section 33, the Adjudicating Authority (“AA”) can now order the immediate dissolution of a corporate debtor if it is clear the company has no meaningful assets. This prevents the wasteful expenditure of time and administrative costs on a “hollow” entity.
5. The “Clean Slate” Doctrine and Immunities
To attract high-quality bidders, the Act strengthens the legal shield provided to the “resolved” company under Section 31.
Fresh Start (Section 31(6))
All prior claims, including those from government departments and regulatory bodies, are extinguished once the resolution plan is approved. This ensures the new owner isn’t blindsided by past liabilities.
Protection of Grants and Licenses (Section 31(5))
The Act mandates that essential business licenses, permits, and registration quotas cannot be terminated or suspended due to the insolvency process. They must continue for their remaining term, ensuring that the company remains operational and valuable to the buyer.
6. Curbing Frivolous Litigation and Delays
Delay is often used as a weapon by defaulting promoters to retain control. The 2026 Act introduces several deterrents:
- Financial Penalties: New Sections 64A and 183A empower the AA to impose penalties up to ₹2 crore on parties who initiate “frivolous or vexatious” proceedings.
- Mandatory Timelines: For Financial Creditors (Section 7), the AA is directed to admit applications within 14 days solely based on the record of default from Information Utilities. If the AA fails to meet this deadline, it must record the reasons for the delay in writing—a measure designed to increase judicial accountability.
7. Advanced Recovery: Avoidance and Fraudulent Trading
The Act sharpens the tools available to recover assets that were illegally moved out of the company before the insolvency began.
Independent Proceedings (Section 26)
One of the biggest flaws in the old system was that “avoidance” applications (to recover undervalued or fraudulent transfers) often died out once the main resolution process ended.
- The Change: Proceedings for fraudulent trading, preferential transactions, or undervalued transfers are now independent. They can continue even after the company has been sold or dissolved. Any money recovered from these actions will be distributed according to the resolution plan or to the creditors, ensuring that “fraud does not pay.”
Extended “Look-Back” Periods
The thresholds for identifying suspicious transactions have been adjusted (Sections 43, 46, and 50). The “look-back” period now counts from the date of initiation rather than the date of admission, catching manipulations that occur while the application is pending in court.
8. Technology and Global Integration
The 2026 Act prepares the IBC for a digital-first future and international cooperation.
- Electronic Portal (Section 240B): The Act mandates the creation of a centralized electronic portal for all IBC procedures. This will host public announcements, claim filings, and progress reports, bringing unprecedented transparency to the process.
- Cross-Border Insolvency (Section 240C): For the first time, a formal enabling provision allows the Central Government to make rules for administering cross-border proceedings. This is vital for pursuing assets located outside India and coordinating with foreign courts when a multinational corporation fails.
9. Expanded Roles for Service Providers
The definition of “Service Provider” (Section 3(31A)) now formally includes Insolvency Professionals (IPs), Agencies (IPAs), and Information Utilities (IUs).
- Disciplinary Oversight: Sections 217–220 have been revamped to allow the IBBI to conduct investigations and impose penalties—including disgorgement of ill-gotten gains—against service providers who fail in their fiduciary duties. This ensures that the professionals running the system are held to the highest ethical standards.
10. Summary Table: Then vs. Now
| Feature | IBC 2016 (Old Regime) | IBC Amendment Act 2026 |
| Asset Sales | Focused on “Whole Company” resolution. | Allows “Piece-meal” or asset-specific resolution plans. |
| Liquidation Authority | Liquidator held most administrative power. | CoC supervises and can replace the Liquidator by 66% vote. |
| Admission of Default | Often required prolonged hearings on “merit.” | Deemed admission based on Information Utility records. |
| Group Entities | Each entity resolved individually. | Framework for coordinated Group Insolvency. |
| Fraud Recovery | Often tied to the CIRP timeline. | Independent proceedings that survive dissolution. |
| Statutory Dues | Ambiguity over “Secured” status. | Strictly excluded from “Security Interest” definition. |
A Strategic Leap Forward
The Insolvency and Bankruptcy Code (Amendment) Act, 2026 represents the maturation of India’s credit culture. By shifting the focus from “procedure” to “value,” the Act recognizes that the ultimate goal of insolvency law is to put productive assets back into the hands of efficient managers as quickly as possible.
For creditors, it offers a faster route to recovery and more control over the liquidation process. For investors, it offers the security of a “Clean Slate” and the ability to buy specific business divisions. For the economy at large, it promises to reduce the “deadweight loss” of stalled companies and endless litigation. As the implementation begins, the success of these amendments will depend on the robust rollout of the Electronic Portal and the continued “commercial wisdom” of the Committees of Creditors.
Pic Courtesy: pegasus/ images are subject to copyright